Trusts and estates attorneys email list
Estate and gift tax planning links tax counsel with attorneys who draft wills and trusts and administer estates.
The tax lawyers email list reaches US attorneys whose records carry the tax practice area, including counsel for IRS audits, Tax Court petitions and transaction planning. Order the file by state, city, ZIP code, role and firm size. Each record includes the firm name, office mailing address, direct phone and Google Business Profile, and 65% include an email verified through ZeroBounce and NeverBounce. Orders begin at 1,000 records, with a free sample and quote first.
Tax work covered
The list includes attorneys whose records carry the tax practice area, from IRS audit and collection counsel to Tax Court litigators and deal planners. The IRS closed 497,621 return audits in fiscal year 2025, and the US Tax Court received 18,549 new cases that year.
The Tax Court's FY 2027 budget justification reports that taxpayers represented themselves in approximately 78% of the cases filed in fiscal year 2025, and that 11,112 of the 18,549 filings were regular cases rather than small tax cases.
Transactional tax work follows the deal. Property sales put tax counsel beside real property law firm contacts, and company acquisitions put them beside M&A attorney contacts.
Direct mail
Yes. The tax attorney mailing list draws on the same records, and 100% of them include a full office address with street, city, state and ZIP code. Firm name, practice area and direct phone share the row, ready for letters, catalogs and event invitations.
Firm size separates a solo tax office from the tax group of a large firm, and role selection sends mail to partners, of counsel or associates. ZIP code selection narrows a tax law firm mailing list to 1 metro area or a single city.
Why vendors sell here
Tax law firms buy tax research services, IRS authorization tools, court e-filing support and return preparation software. Their work runs through federal systems: Form 2848 authorizations in the IRS Centralized Authorization File, and petitions in DAWSON, the Tax Court's electronic filing and case management system.
Field coverage
Tax lawyer contact data includes firm name, practice area, direct phone, full mailing address and Google Business Profile on every record. Google ratings reach 97%, websites 86% and verified emails 65%, and each file adds bar number, bar admission state, job title, LinkedIn profile and firm size.
| Field | Coverage bar | Share of records |
|---|---|---|
| Firm name | 100% | |
| Full mailing address | 100% | |
| Direct phone number | 100% | |
| Practice area | 100% | |
| Google Business Profile | 100% | |
| Google rating and reviews | 97% | |
| Website | 86% | |
| Verified email | 65% | |
| Facebook page | 52% | |
| Instagram handle | 33% |
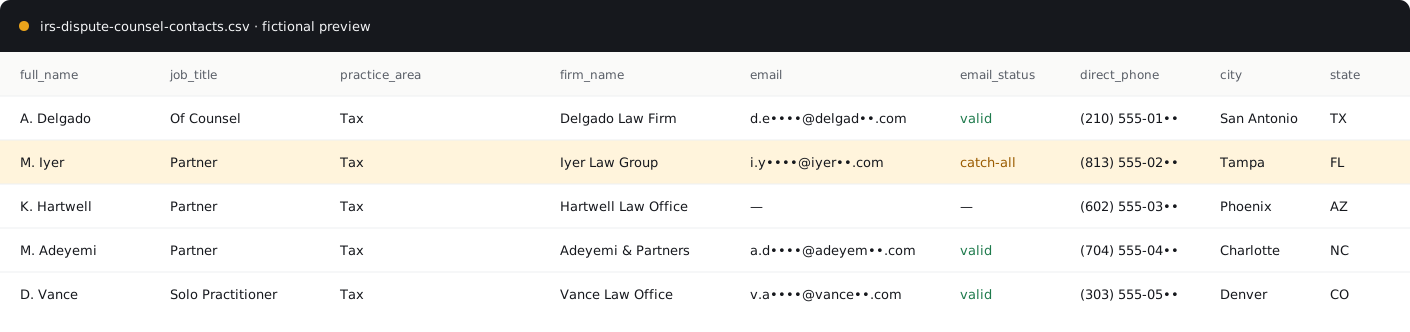
Also in every file: bar number, bar admission state, job title, LinkedIn profile, firm size and an email status column that flags catch-all addresses.
Fill rates cover all 1,000,000 records. Bar number and bar admission state are the same 2 licensing details an attorney enters on IRS Form 2848, and a free tax sample shows those columns for your states.
IRS practice rights
Attorneys, certified public accountants and enrolled agents hold unlimited representation rights before the IRS. Under Circular 230 at 31 CFR 10.3, an attorney not under IRS suspension or disbarment practices by filing a written declaration of qualification and authority, made in Part II of Form 2848.
Circular 230 defines an attorney as a member in good standing of the bar of the highest court of any state, territory, possession or the District of Columbia. On Form 2848, an attorney uses designation a and enters the 2-letter licensing jurisdiction with the bar or license number.
The IRS assigns each representative a Centralized Authorization File (CAF) number: 9 digits, separate from the SSN, EIN and PTIN, and not by itself proof of authority to practice. A PTIN is a separate duty that applies to anyone who prepares federal tax returns for compensation.
The U.S. Tax Court keeps its own bar. Attorneys apply on Form 30 with a $50 fee and a certificate of good standing issued within 90 calendar days, while nonattorneys qualify by passing the Court's examination under Rule 200. By statute, the Court has 19 judges appointed by the President to 15-year terms.
By state
Yes. Tax lawyers are available in all 50 states and their cities, with ZIP code selection for a single metro area. State choice is 1 of 4 pricing factors, next to record count, selected fields and practice area.
Combine any of the 50 states in a tax lawyer selection; the quote reflects the states included.
Related lists and guides
Describe the tax practices, states and seniority your outreach targets. A free sample and quote follow within 1 hour, Monday to Friday, 9am–6pm UTC.
Questions
No. The database holds US attorneys only. Certified public accountants and enrolled agents share unlimited IRS representation rights with attorneys under Circular 230, and they sit outside this file as separate professions.
Bar number and bar admission state come with every tax lawyer record, without a published fill rate. Job title, LinkedIn profile and firm size sit beside them, and the practice area column marks the tax segment.
ZeroBounce and NeverBounce test each email, and the team compares attorney details with state bar websites. The last full verification ran on September 10, 2026, with monthly refreshes and deduplication.
Yes. City and ZIP code selections isolate IRS dispute and tax planning attorney contacts in 1 market once the selection reaches 1,000 records, and role or firm size narrows it further.
Payment goes through PayPal, bank transfer, invoice or cryptocurrency, and the CSV or Excel file arrives by email within 2 hours after it clears. All sales are final under a 12-month license that bars resale.